

MyBambu - Better than Banking
Bambu
- 4.5
- 11.09K Reviews
- 1.00M
- Downloads
- Free
- Price
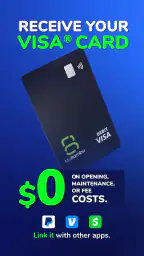
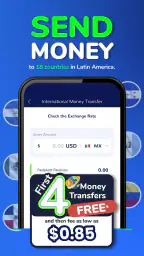
Screenshots
MyBambu - Better than Banking Pros and Cons
Pros
- No monthly fees or minimum balance.
- Instant money transfers to friends.
- User-friendly interface.
- Free ATM withdrawals nationwide.
- Virtual card for online purchases.
Cons
- Limited customer support hours.
- No physical branches available.
- Requires stable internet connection.
- Limited international transfer options.
- No interest on account balances.
 Analysis by All-app
I judge a finance app less by the excitement of its first few days than by whether it still earns a place on my phone once the novelty wears off. That is the question I kept coming back to with MyBambu: does bringing everyday money tasks together make life simpler over time, or does it become one more account to check and maintain? My impression is that it can be useful for people who want a mobile-first way to handle several financial needs, but its long-term value depends on which of those needs they actually use.
MyBambu is a free finance app from Bambu, rated for Everyone, and it has built a sizeable audience: more than a million installs, with an average rating of 4.5 from around 43,000 ratings. It first appeared in June 2020, and version 4.8.5 is the current release. Those figures give a sense of an established product, but they don’t tell me whether it suits a particular person. The more practical question is whether its mix of services fits your routines better than the banking app you already have.
The first-week appeal is convenience
Ever felt like traditional banking just isn’t cutting it for you anymore? Let me introduce you to MyBambu, an app that's been making waves in the financial tech world by offering features that rival even the best banks out there. You're probably wondering, "What makes this app so special?" Well, let me take you on a little journey through my experience with it.
Revolutionizing the Banking Experience
First off, MyBambu is all about convenience and accessibility. Straight out of the gate, the app is super easy to download and set up. I had my account up and running in just a few minutes, which is a godsend for someone like me who doesn’t have the patience to jump through hoops. The user interface? Slick and intuitive, perfect for both tech newbies and veterans.
A quick setup is a nice opening, but I wouldn’t treat it as proof that every financial task will be effortless. A good first test is to try one ordinary action you expect to repeat, such as checking your balance or making a transfer, and see whether the steps make sense to you. If you’re opening an account for a specific purpose, check the relevant terms and eligibility before moving money; a smooth welcome screen is not a substitute for understanding how a financial service works.
Your Wallet's New Best Friend
One of the standout features of MyBambu is its comprehensive suite of financial services. It’s not just about storing money; you can pay your bills, transfer money internationally, and even get a virtual or physical debit card. And get this – it supports multiple currencies, which is a huge plus if you’re like me and love to travel. Imagine being able to manage all your finances from one place without having to worry about currency conversion headaches!
That combination is most useful when it matches a real pattern in your life. For example, someone who regularly pays bills, sends money abroad, and wants a card may value having those jobs close together more than someone who only needs a place to receive a paycheck. A practical way to assess the app is to list the transactions you make in a typical month and identify which ones you would genuinely move here. If only one rare task fits, keeping your existing bank as the main hub may be less work.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
International transfers and multiple currencies can be especially relevant to people supporting relatives overseas or splitting expenses across borders. Before relying on any app for a time-sensitive payment, though, check the recipient details, applicable charges, exchange rate, and expected delivery timing shown for that transaction. Currency support can reduce the need to juggle separate services, but it does not automatically make every transfer cheaper or quicker than another provider. I would compare the final amount the recipient gets, not just the convenience of starting the transfer in the same app.
A virtual card can also be handy for separating online spending from everyday purchases, while a physical card is more useful when you want to pay in person. Those are different habits, so I’d choose based on how I actually spend rather than treating both as essential. If you use a card for recurring subscriptions, keep a simple note of which payments are attached to it; that makes it easier to spot what needs updating if you change cards or stop using the account.
What really blew me away, though, is their commitment to offering services that traditional banks charge an arm and a leg for. With MyBambu, there are no hidden fees, which, let’s be honest, is a breath of fresh air in today’s banking world. They even offer cash back on certain transactions, making it not just a banking app but a smart way to manage your finances.
For ongoing use, I’d avoid building a budget around cashback until I had checked which transactions qualify and whether the offer fits spending I would have done anyway. A reward is only valuable if it does not nudge you into buying something unnecessary. Likewise, it is sensible to review the current fee and account terms before making this your primary place for money: fees and conditions can depend on the service or transaction, so I would not interpret a general impression of low-cost banking as a promise that every possible action is free.
Month-to-month value comes from a repeatable routine
The app has a better chance of lasting on my phone if I give it a defined job. I might use it for a recurring bill and a regular international transfer, then check whether those tasks are genuinely easier to manage together. A short monthly review can answer the important questions: did I use the features I expected, were the transfers and card activity easy to track, and did the account save me a step without creating another chore? If the answer stays yes, the convenience is recurring rather than just a first-week impression.
For an everyday scenario, imagine that payday arrives, a household bill is due, and a family member abroad needs money later in the month. MyBambu’s combination of bill payment, transfers, and card access may make it a natural place to handle several of those tasks. I would still check the bill confirmation and transfer details before submitting anything, then keep the receipt or confirmation where I can find it. That small habit matters more than a polished interface when I need to verify that a payment went through.
Compared with a conventional bank app, the appeal here is the possibility of bringing a broader set of money tasks into one mobile account. A traditional bank may be the better home for someone whose priority is an existing relationship, familiar account services, or a routine already organized around that provider. Compared with using separate money-transfer and card apps, MyBambu may reduce switching between tools, but combining tasks only helps if the app’s terms and workflow suit each one. I would compare the actual service I need rather than assume that “all in one” means best in every category.
It is also worth deciding what role the account should play before moving your whole financial life into it. Some people will be comfortable using one account for daily spending; others may prefer to keep their primary bank and use MyBambu only for a particular transfer or card purpose. That second approach can be a sensible trial: it lets you learn the app’s workflow without making an unfamiliar service responsible for every payment at once.
Maintenance is manageable, but it is still your responsibility
Any finance app asks for a little upkeep, even when the interface feels straightforward. I would keep contact and account details current, review transactions regularly, and make sure I can still access the account before relying on it for a deadline. If a payment method or recurring bill changes, updating it promptly helps avoid the annoying gap between thinking a payment is covered and knowing it is covered.
Security deserves the same practical attention. The original review describes protections such as two-factor authentication and encryption, but I would still use a strong, unique password, protect access to the phone, and avoid signing in on a device I do not control. If anything looks unfamiliar, I would pause and contact support through a channel I trust instead of sharing account details in response to an unexpected message. Good security is a combination of the app’s safeguards and the choices I make around it.
Customer service can matter most when something breaks the routine, not when everything is working normally. The original experience with support was positive, including help with linking a bank account, which is encouraging. For my own use, I would keep a record of a support conversation and any payment confirmation if an issue concerns a transfer or bill. That gives me a clear reference point if I need to explain what happened later.
Where the convenience can turn into fatigue
The main risk is not that a financial app has several tools; it is that I may start checking another balance, tracking another card, and remembering another set of account details without gaining enough in return. Notifications and account reviews can become noise if I have no clear reason to open the app. I would keep only the alerts that help me act, and make a deliberate decision about which account is responsible for each regular payment.
There is also a difference between having a feature and finding it suitable for every situation. A travel purchase, a routine bill, and an urgent transfer each have different stakes. Before using MyBambu for an important transaction, I would check the terms and details on that particular screen and leave enough time for a payment that cannot be delayed. If I need a specialized service or a particular account feature, I would compare providers directly instead of choosing based only on the convenience of having fewer apps.
This is probably not the right fit for someone who wants to keep all their banking inside a familiar traditional provider, has no use for the transfer or card options, or dislikes managing accounts on a phone. It may also be a poor match if you expect one app to remove every financial decision: you still need to check charges, understand currency conversion, protect sign-in details, and confirm that payments have completed. For those users, a simple account with an established routine may feel easier than adding another service.
Security You Can Trust
Now, I know what you’re thinking. With all these features, how secure is it? Rest assured, MyBambu takes security very seriously. They’ve implemented top-notch security protocols to ensure your data is safe. From two-factor authentication to encryption, they have all the bases covered. It feels good knowing that my financial information is secure, especially in a digital age where data breaches are all too common.
Customer Support That Cares
Another thing I loved about using MyBambu is their customer support. It’s not just about having a chat feature; it’s about having real people ready to help you out whenever you need it. I had a small issue with linking my bank account, and their support team resolved it quickly and efficiently. It’s rare to find such dedicated customer service, which makes the app even more appealing.
In conclusion, if you’re tired of the same old banking routine and want something that adapts to your lifestyle, MyBambu is definitely worth checking out. It’s more than just a banking app; it’s a comprehensive financial tool that empowers you to take control of your money. So go ahead, give it a try, and you might just find yourself wondering how you ever managed without it!
My long-term verdict
I would recommend MyBambu to someone who can name two or three recurring tasks it would simplify, especially if those include bills, international transfers, or card use. The app’s mix of services gives it a clear reason to be considered, and its free entry point makes trying it less of a commitment. I would start with one low-stakes task, learn how confirmations and account activity are presented, and expand only if the routine feels dependable.
If your needs are limited to checking a balance or making an occasional transfer, a provider you already use may be more convenient than maintaining a new account. If you do try it, think of long-term value as a habit question: does it make a regular financial task clearer, easier, or less fragmented? When the answer is consistently yes, it earns its place. When it merely adds another screen to check, it is reasonable to move on.
Frequently Asked Questions
What is MyBambu and how does it differ from traditional banking?
MyBambu is a digital banking app designed to provide more accessible financial services compared to traditional banks. It offers features like no-fee accounts, easy money transfers, and a mobile-first approach, making it ideal for those who prefer managing finances on their smartphone without the hassle of visiting a physical bank branch.
Is MyBambu safe to use for online banking?
Yes, MyBambu prioritizes user security by implementing advanced encryption technologies to protect your financial information. The app complies with industry standards and regulations to ensure your data is safe from unauthorized access, providing peace of mind while you manage your finances online.
What features does MyBambu offer to users?
MyBambu offers a wide range of features including free account setup, no monthly fees, free money transfers, and the ability to pay bills directly through the app. Additionally, users can benefit from a user-friendly interface and customer support available in both English and Spanish, catering to a broader audience.
Are there any fees associated with using MyBambu?
MyBambu is designed to be a cost-effective solution for users, with no monthly maintenance fees or charges for standard account activities such as money transfers and bill payments. However, users should review the app’s terms and conditions for any exceptions that may apply to specific services.
How can I get started with MyBambu?
Getting started with MyBambu is simple. Download the app from the Google Play Store or Apple App Store, sign up with your personal information, and verify your identity. Once your account is set up, you can start enjoying the benefits of digital banking, such as free money transfers and bill payments, right from your smartphone.


